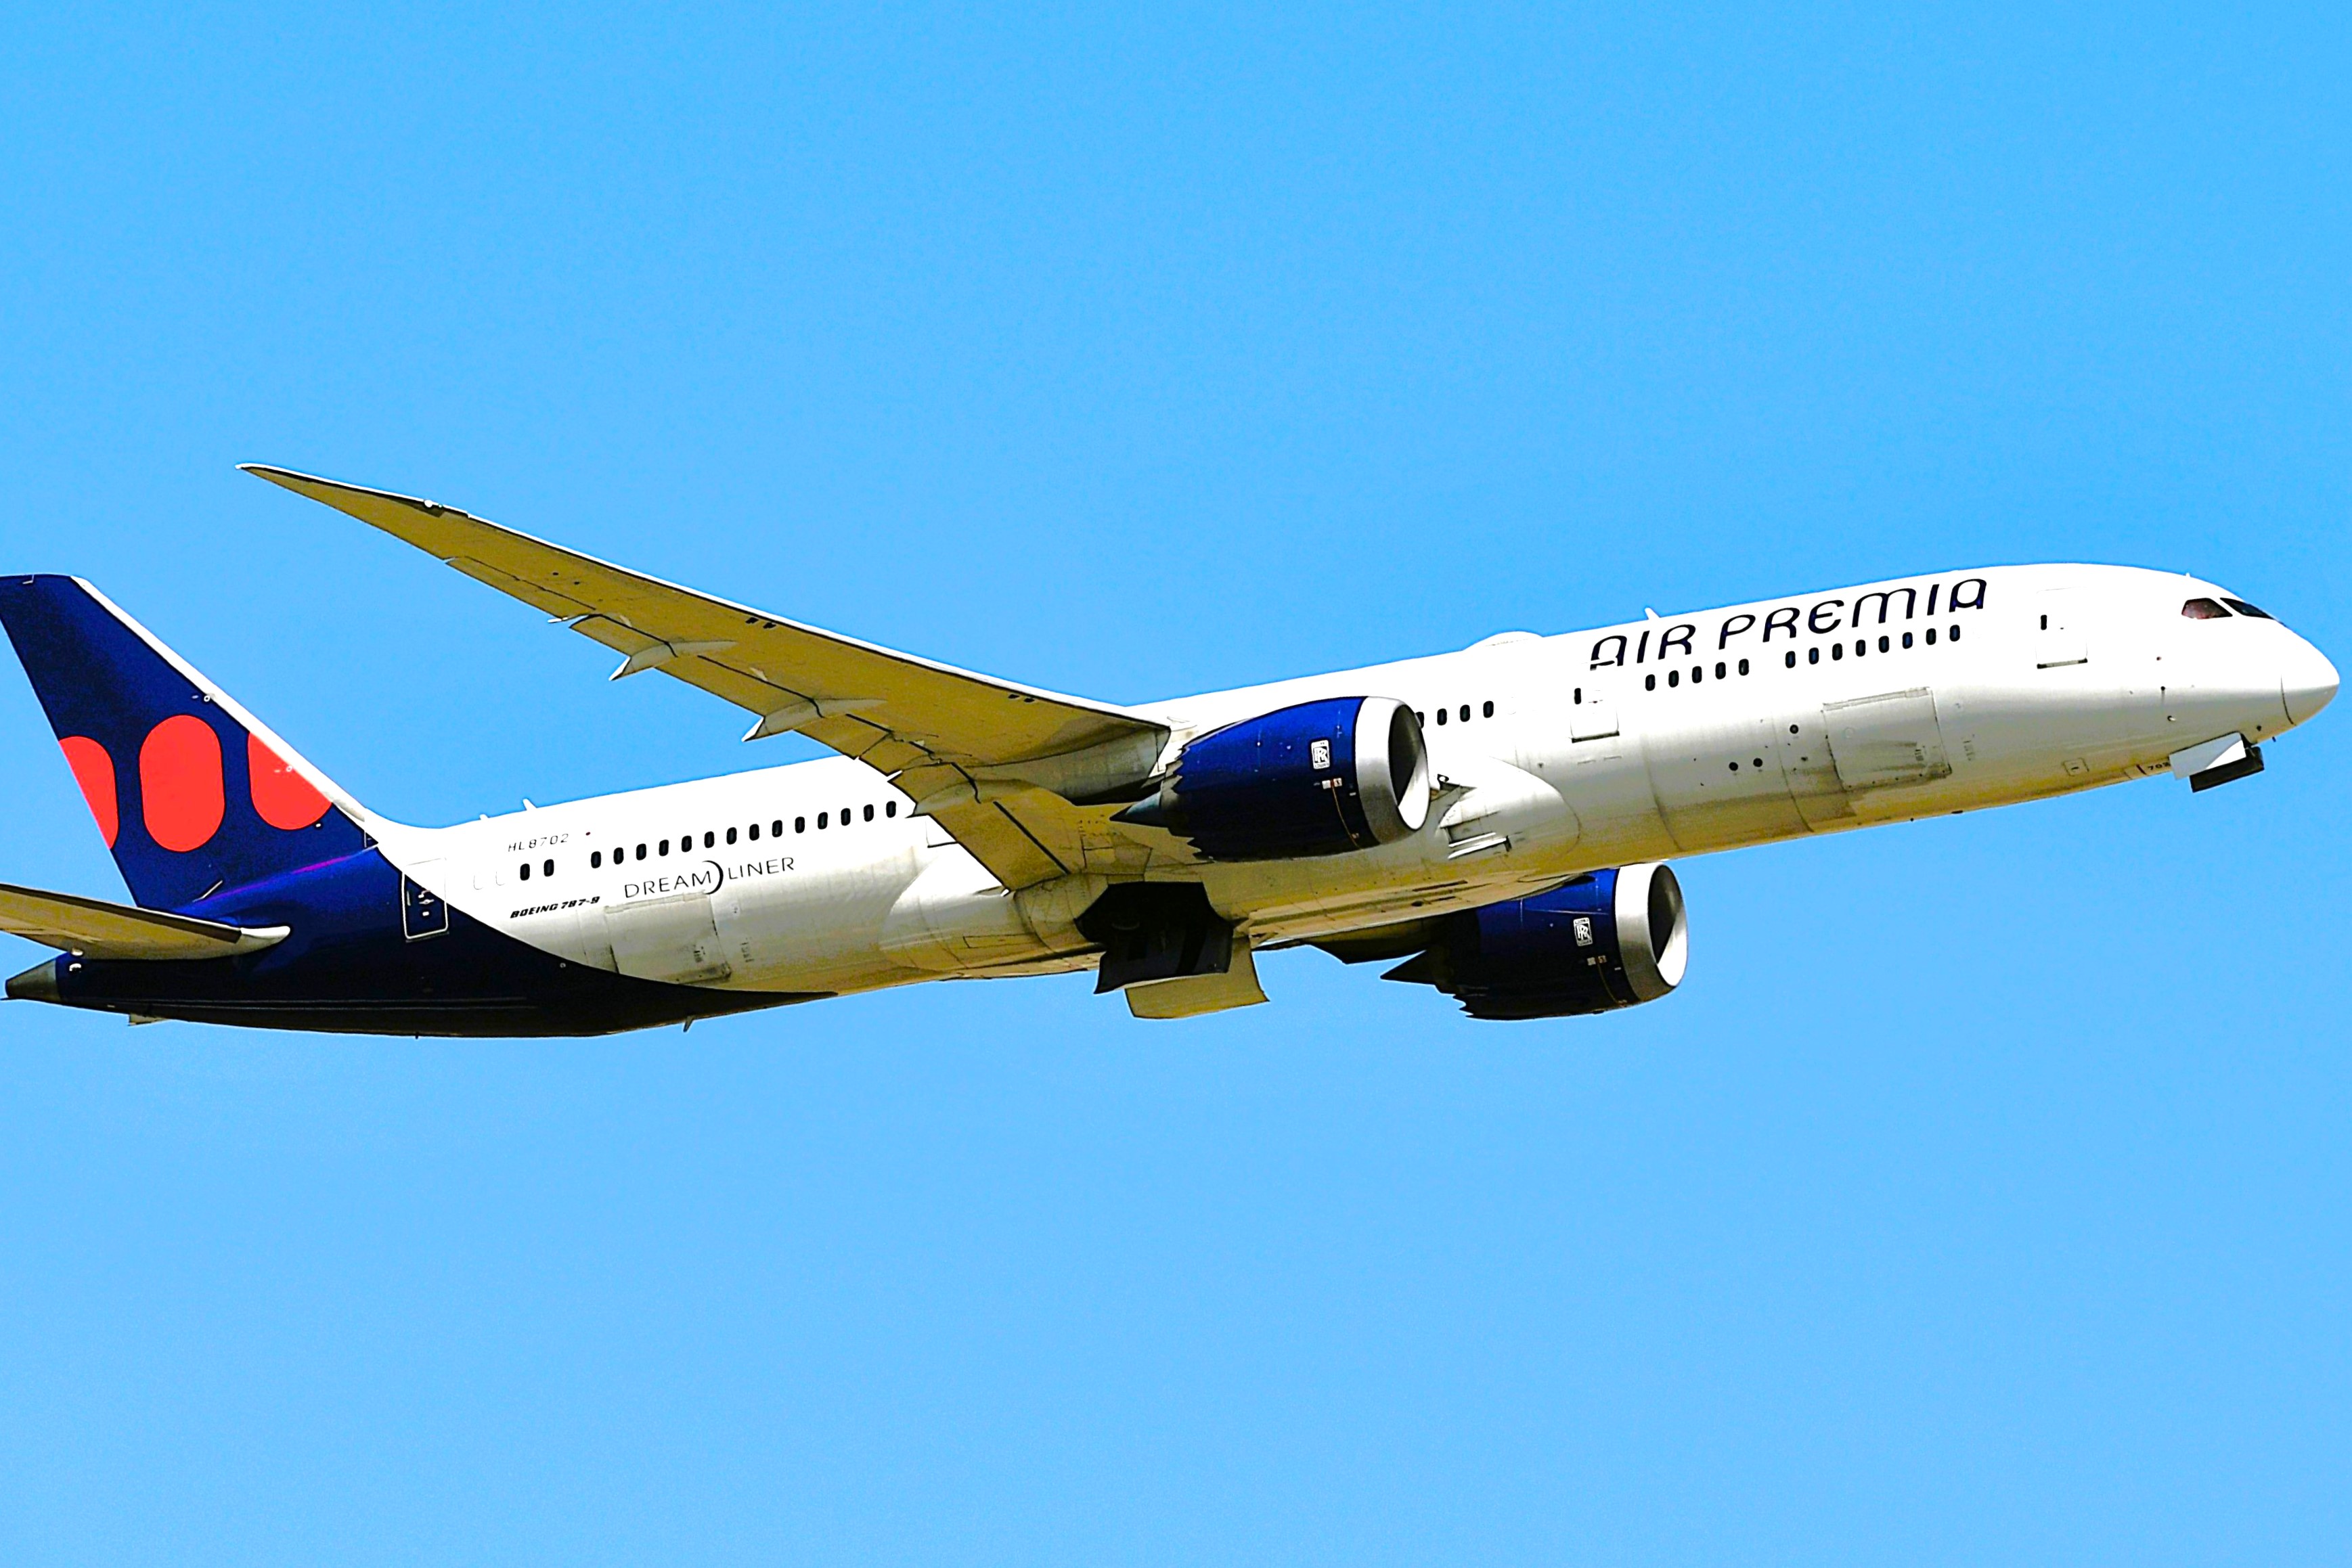
South Korean private equity firm VIG Partners is moving to acquire Air Premia, with negotiations reportedly underway for a controlling stake in the long-haul-focused hybrid carrier as the country’s low-cost airline sector enters another phase of consolidation.
According to South Korean aviation and investment-banking industry sources cited on September 16, 2026, VIG Partners is negotiating with AP Holdings and Tire Bank to acquire approximately 70% of Air Premia’s management-control shares. The reported stake comprises around 48% held by AP Holdings and 22% held by Tire Bank, with the transaction value said to be in the ₩300 billion range, equivalent to roughly $219 million at current exchange rates.
VIG has reportedly appointed Bain & Company as its acquisition adviser and has already begun due diligence on Air Premia. The negotiations remain ongoing, however, and Tire Bank has stated that no decision has been made regarding a sale.
Founded in 2017, Air Premia developed a hybrid airline model designed to combine selected premium services associated with full-service carriers with the lower fares traditionally offered by LCCs.
Its strategy has centered on long-haul flying using the Boeing 787-9 Dreamliner, distinguishing the airline from South Korea's predominantly short- and medium-haul LCC operators.
Air Premia has expanded its network to North America and is currently described by South Korean industry sources as the country's only LCC operating scheduled routes to the United States, including New York, Los Angeles and Washington.
The carrier's long-haul strategy has also been supported by its expanding 787-9 fleet and international network, giving it a different operating profile from carriers such as Eastar Jet, which has historically focused more heavily on short-haul markets.
Air Premia's shareholder structure has changed substantially since the airline began expanding.
Tire Bank Group formally announced in May 2025 that it had acquired an additional 22% stake from JC SPC and Sono International, taking the group’s total ownership to more than 70% and making it Air Premia's controlling shareholder.
The latest reported transaction structure, however, identifies AP Holdings and Tire Bank as the holders of approximately 70% of the management-control shares targeted by VIG.
AP Holdings is an investment company whose major shareholders reportedly include Tire Bank Chairman Kim Jeong-gyu and members of his family.
The ownership situation therefore reflects a series of transactions through which Air Premia moved from its earlier investor structure toward control by the Tire Bank-related group.
Air Premia has also been working to strengthen its balance sheet.
In July 2026, the airline announced a ₩110 billion paid-in capital increase through a shareholder-allocation offering. The company plans to issue 550 million new common shares, with the proceeds intended to improve its financial structure and provide a more stable foundation for operations.
Air Premia cited continued uncertainty in the aviation industry, including currency movements and fuel-price volatility, as reasons for the capital strengthening. The airline also linked the move to its longer-term growth strategy, including plans for new Asian routes during the winter season.
According to the South Korean industry reporting surrounding the potential sale, Tire Bank Chairman Kim Jeong-gyu had continued supporting Air Premia during a three-year prison sentence related to a tax-evasion conviction. The report said he paid the remaining balance for the Air Premia acquisition in September 2025 and subsequently participated in the ₩110 billion capital increase announced in July 2026. The same report suggested that high fuel prices and the financing burden associated with continued management contributed to the emergence of a possible sale, while Tire Bank said that nothing had been decided.
For VIG Partners, acquiring Air Premia would represent its second South Korean LCC investment.
The private equity firm acquired Eastar Jet in 2023. A purchase of Air Premia would therefore come only three years after that transaction.
The strategic rationale reported by Korean industry sources is the possibility of combining the complementary characteristics of the two carriers.
Eastar Jet has a network profile centered more heavily on short-haul markets, while Air Premia has built a long-haul operation around the Boeing 787-9.
A common ownership structure could therefore potentially provide opportunities to share commercial resources, strengthen network connectivity and pursue greater economies of scale. However, any operational integration, merger or restructuring of the two airlines has not been announced as part of the reported Air Premia negotiations. The economies-of-scale rationale is an industry interpretation of the potential transaction rather than a confirmed VIG plan.
The potential acquisition comes as South Korea's LCC sector prepares for another major structural change.
Jin Air, Air Busan and Air Seoul have agreed to merge, creating a unified airline under the Jin Air brand. The three carriers approved their merger agreements in August 2026 and are targeting a launch of the integrated airline on March 17, 2027, subject to shareholder and regulatory approvals.
The merger will bring together the fleets, routes, employees, assets and operating capabilities of the three airlines. Jin Air will absorb Air Busan and Air Seoul, creating a substantially larger LCC platform.
Industry analysis has indicated that the combined airline could operate around 59 aircraft initially, making it South Korea's largest LCC by fleet size. The three carriers are also expected to seek economies of scale by combining their networks and operational resources.
This development is important for VIG because the potential Air Premia acquisition would occur only months before the planned launch of the integrated Jin Air.
South Korea's LCC landscape is consequently moving toward larger airline groups, with scale becoming increasingly important for fleet utilization, purchasing, network development and competition across domestic and international markets.
Air Premia's evolution has been rapid.
The airline introduced its first Boeing 787-9 in 2021 and subsequently developed a network stretching from Northeast Asia to North America. Its U.S. network now includes major destinations such as Los Angeles, New York and Washington.
The carrier has simultaneously expanded its Asian network and increased frequencies on established routes.
The 787-9 is central to this strategy. Operating a common widebody fleet gives Air Premia a substantially different cost and network structure from Korean LCCs primarily using narrowbody aircraft on short- and medium-haul routes.
That distinction is also what makes the airline potentially complementary to an operator such as Eastar Jet.
The potential VIG-Air Premia transaction is occurring alongside a broader restructuring of South Korea's airline industry.
At the full-service end of the market, Korean Air and Asiana Airlines are moving toward integration, with the combined carrier scheduled to operate under the Korean Air brand following the completion of the merger process.
At the LCC level, Korean Air's affiliated carriers Jin Air, Air Busan and Air Seoul are being consolidated into a single airline scheduled to launch in March 2027.
That leaves independent carriers such as Jeju Air, T'way Air, Eastar Jet, Air Premia and Aero K operating in an increasingly concentrated competitive environment.
Against this background, VIG's reported interest in Air Premia could become another important step in the reshaping of South Korea's LCC sector.
The immediate focus will be on the outcome of VIG Partners' due diligence and negotiations with AP Holdings and Tire Bank.
The reported ₩300 billion transaction value and approximately 70% controlling stake are not yet finalized, and the transaction could still change or fail to proceed. Tire Bank has specifically said that no decision has been made.
If an agreement is ultimately reached, VIG would become the controlling investor behind two distinctive South Korean LCC businesses: Eastar Jet, with its predominantly short-haul network, and Air Premia, with its Boeing 787-based long-haul operation.
The potential deal would also arrive at a pivotal moment for the Korean aviation market, with the planned March 2027 launch of the integrated Jin Air creating a significantly larger LCC competitor.

.jpg)